DAX rises to 25,278 – defence leads, chip stocks weak; slightly lower start seen Tuesday
The DAX gained 0.76% on Monday. Rheinmetall led, Infineon fell. VW shares rose despite a slump in deliveries. IG sees the DAX slightly lower on Tuesday; final inflation data are due at 08:00.
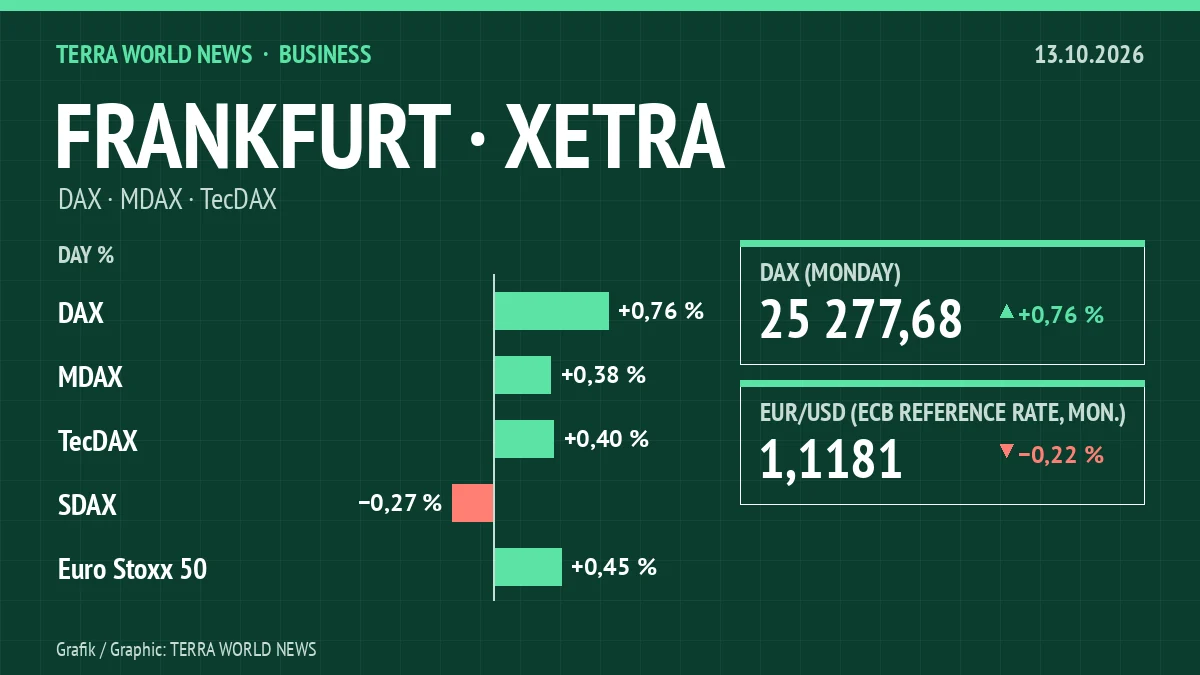
The DAX benchmark index (Germany's 40 largest listed companies) closed 0.76% higher at 25,277.68 points on Xetra on Monday, extending Friday's gains. The MDAX (mid-caps) rose 0.38% to 30,104.33 points and the Euro Stoxx 50 gained 0.45% to 6,201.21. The TecDAX added about 0.4%, while the SDAX (smaller companies) slipped about 0.3%. According to dpa-AFX, investors welcomed Chancellor Merz's call for a lower electricity tax. A CMC Markets analyst nevertheless called the recovery shaky, citing worries about financing huge AI investments, high bond yields and expensive energy.
Rheinmetall was the best DAX stock, up 2.5%. According to dpa-AFX, Morgan Stanley sees scope for a year-end rally in defence stocks; in the MDAX, Hensoldt rose 5.8%. Chip stocks were weak: Infineon lost 2.8% and was the worst DAX performer. Volkswagen reported 14.3% fewer third-quarter deliveries (1.87 million vehicles), and 38.5% fewer in China. The shares still rose 0.6%, Dow Jones reported. Deutsche Telekom, which slumped on Friday by almost 8% over SpaceX's entry into the US mobile market, was the most traded DAX stock on Monday. Outside the DAX, Nordex rose 3.9% on strong orders, while Aroundtown fell 5.7% after a Goldman Sachs downgrade.
The euro weakened: the European Central Bank set its reference rate at 1.1181 dollars (Friday: 1.1206). According to dpa-AFX, weak European economic data, worries about France's finances and speculation about higher US interest rates are weighing on the currency.
For Tuesday, broker IG expects a slightly weaker start: according to dpa-AFX (shortly before 07:00), IG indicated the DAX 0.16% lower at 25,237 points. In Asia, chip stocks are falling after sceptical remarks by Broadcom's CEO about AI spending; Tokyo's Nikkei was down 2.2% (finanzen.at, as of 07:11 CEST), and Seoul was down as much as 6.3% according to Dow Jones. At 08:00 the Federal Statistical Office publishes the final September inflation rate (preliminary: 3.3%), and Porsche holds a pre-close call with analysts. From midday, JPMorgan, Goldman Sachs, Citigroup and Wells Fargo report quarterly results. The ZEW index is not due until 20 October.
| Index | Close | Day % |
|---|---|---|
| DAX | 25,278 | +0.76 % |
| MDAX | 30,104 | +0.38 % |
| TecDAX | 3,993 | +0.40 % |
| SDAX | 18,049 | −0.27 % |
| Euro Stoxx 50 | 6,201 | +0.45 % |
| Company | Price (EUR) | Day % | Reason |
|---|---|---|---|
| Rheinmetall | 962.20 | +2.46 % | Morgan Stanley sees scope for a year-end defence rally |
| RWE | 59.26 | +2.28 % | – |
| SAP | 194.46 | +1.57 % | – |
| Fresenius | 43.00 | +1.52 % | – |
| Hannover Rück | 267.00 | +1.44 % | – |
| Continental | 68.60 | −0.78 % | – |
| BASF | 51.27 | −0.79 % | – |
| Mercedes-Benz | 39.27 | −0.82 % | carmakers slightly lower |
| Daimler Truck | 41.00 | −0.85 % | – |
| Infineon | 57.22 | −2.79 % | chip stocks under pressure: doubts over returns on AI spending |
| Company | Day % (approx.) | Reason |
|---|---|---|
| Volkswagen (DAX) | +0.6 % | Q3 deliveries −14.3% (China −38.5%) – market largely shrugged |
| Hensoldt (MDAX) | +5.8 % | defence stocks in demand |
| Nordex (TecDAX) | +3.9 % | Q3 order intake up almost 30% |
| Schaeffler (MDAX) | +1.2 % | job cuts completed earlier |
| Aroundtown (MDAX) | −5.7 % | Goldman Sachs downgrade to "sell" |
| Market | Level | Change % | Time / source |
|---|---|---|---|
| DAX indication (IG) | 25,237.00 | −0.16 % | approx. 06:57 CEST, dpa-AFX |
| DAX future (Eurex) | 25,372.00 | – | approx. 05:54 CEST, Dow Jones: −30 points |
| Nikkei 225 | 67,501.10 | −2.22 % | as of 07:11 CEST, finanzen.at |
| Hang Seng | 24,176.05 | −0.39 % | as of 07:11 CEST, finanzen.at |
| Kospi | 5,983.54 | −6.30 % | 06:35 CEST, Dow Jones |
| Brent (USD/barrel) | 105.35 | −1.20 % | 06:35 CEST, Dow Jones |
| Time | Event |
|---|---|
| 07:00 | Fraport: September traffic figures |
| 08:00 | Germany: September consumer prices, final (forecast +3.3% y/y); Porsche: pre-close call |
| 11:30 | German federal bond auction (EUR 5bn, maturing October 2031) |
| 11:55–14:00 | JPMorgan, Goldman Sachs, Citigroup, Wells Fargo, Johnson & Johnson, UnitedHealth: results; BMW: pre-close call |
| 16:00 | US: September existing home sales |
| 20 Oct, 11:05 | ZEW economic sentiment (following week) |
For information only, not investment advice. Prices as of the time stated, not real-time quotes.
Sources
- dpa-AFX via onvista: ROUNDUP/Aktien Frankfurt Schluss – Dax erholt sich weiter (12.10.2026)
- dpa-AFX via finanzen.at: ROUNDUP/Aktien Frankfurt Schluss – Dax erholt sich weiter (12.10.2026)
- Dow Jones via finanzen.net: XETRA-SCHLUSS/DAX weiter auf dem Weg nach oben (12.10.2026)
- finanzen.net: Handel in Frankfurt – DAX verbucht schlussendlich Zuschläge (12.10.2026, 17:57)
- finanzen.at: TecDAX zum Ende des Montagshandels mit Zuschlägen (12.10.2026)
- finanzen.net: SDAX schlussendlich schwächer (12.10.2026, 17:57)
- Dow Jones via finanzen.at: Volkswagen-Absatz sinkt im 3. Quartal um 14 Prozent (12.10.2026, 08:50)
- dpa-AFX via finanzen.at: Devisen (EZB-Richtwerte) – Euro-Referenzkurs bei 1,1181 US-Dollar (12.10.2026)
- dpa-AFX via MarketScreener: Devisen – Eurokurs fällt wieder unter 1,12 US-Dollar (12.10.2026)
- 4investors: Deutsche Telekom Aktie – Nach dem Absturz kommt die Ruhe (12.10.2026, 09:59)
- dpa-AFX via onvista: DAX-FLASH – Leicht schwächer im angespannten Umfeld (13.10.2026)
- Dow Jones via finanzen.ch: EUREX/DAX-Futures im Frühhandel mit leichten Abgaben (13.10.2026)
- Dow Jones via finanzen.at: MÄRKTE ASIEN – Chipwerte unter Abgabedruck, Börse Seoul verliert 6,3% (13.10.2026, 06:35)
- finanzen.at: Asiens Börsen in Rot (13.10.2026, 07:11)
- Dow Jones via finanzen.net: TAGESVORSCHAU/Dienstag, 13. Oktober
- Destatis: Inflationsrate im September 2026 voraussichtlich +3,3 %